Club 720 connects consumers with lenders, programs, products and housing opportunities that can help them reach their housing goals.
For lenders, the Marketplace creates an opportunity to bring financing solutions into communities where we are actively identifying what residents can afford, where financing barriers exist and which products can help close those gaps.
Housing affordability isn’t determined by sale price alone. The financing matters. Through Club 720 and the H.O.M.E. Method, communities examine the relationship between household purchasing power, monthly payment, cash to close, available assistance and the housing being produced. Lenders help us answer a critical question:
Club 720 works with communities, housing partners, employers, lenders, counselors, builders, and residents to better understand the local housing marketplace.
During a H.O.M.E. Method installation, communities identify:
Understand Demand: We identify what residents are trying to accomplish, what they can afford and the barriers standing between them and their housing goals.
Map Available Financing: We identify mortgage products, assistance, employer benefits and other resources available within the market.
Find the Best Available Fit: We evaluate where existing products can serve the need—including where resources can work together.
Identify the Remaining Gap: When the marketplace cannot fully solve the problem, communities can see more clearly where an intervention may be justified.
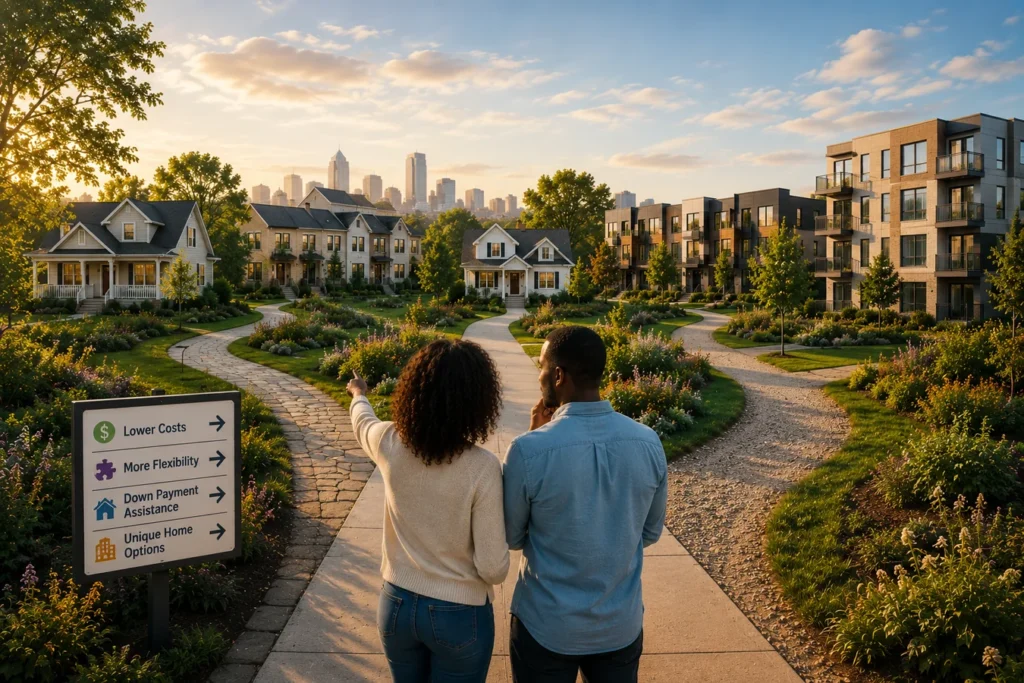
That is why Club 720 uses a Best Available Fit approach.
We look for the best available value for the consumer, the best available solution for the identified need and the best available contribution to the local housing marketplace. A product may be a strong fit because it offers lower costs. Another may provide more flexible qualification. Another may work with down payment assistance. Another may finance a housing type other lenders cannot serve.
The goal is not to crown one lender as the winner. The goal is to create meaningful choices for consumers.
Best Available Fit is not a lender ranking. It is a matching framework based on the consumer’s goal, affordability, eligibility and available resources.
Club 720 seeks lending products that provide strong value to consumers and expand the choices available within the marketplace. We generally consider several factors:
We look beyond the advertised interest rate. Relevant considerations may include:
We also consider who can actually use the product. This may include:
One of the strengths of Club 720 is helping consumers identify resources that may work together. Where permitted, we value products that can be combined with:
A product may be particularly valuable because it solves a gap that other products do not. Examples might include financing for:
We also consider whether the product creates a meaningful advantage for the consumer compared with other available options. That advantage might come from lower borrowing costs, reduced cash to close, greater underwriting flexibility, access to a particular housing type or another material benefit.
Approved institutions may nominate a designated mortgage professional to represent the institution within Club 720. Approved products belong to the participating institution, not to an individual loan officer.
The participating bank, credit union or mortgage institution.
Products determined to provide value within the local Marketplace.
The institution’s nominated mortgage professional who may serve Club 720 consumers.
Each participating community adopts a Platform Inclusion and Governance Policy establishing consistent standards for Marketplace participation.
Products are evaluated based on factors such as:
Participation is not determined by sponsorship, advertising spend, institutional size, market share or personal relationships.
Your participation helps us understand more than which mortgages are available. Together, we can identify:
→ Which households the existing lending market can serve.
→ Where cash-to-close remains a barrier.
→ Where underwriting or property requirements limit access.
→ Which assistance programs actually improve affordability.
→ Where products can be stacked to solve a gap.
→ Which housing types are difficult to finance.
→ Where construction or development financing is limiting supply.
→ Where a true financing gap remains.
The strongest Marketplace lenders do more than originate loans. They help strengthen the housing delivery system. They may:
Marketplace participation comes with responsibilities. Participating lenders are expected to help maintain a high-quality consumer experience. Expectations may include:
• Following applicable lending, fair housing, consumer protection, privacy, and Marketplace requirements.
A Marketplace Seat is maintained through active participation and service.
No. Club 720 does not sell leads and does not guarantee referral volume. Marketplace participation gives a qualified lender the opportunity to serve consumers whose housing goals may align with the lender’s products. Consumers maintain the right to:
• Select the financing provider they believe best meets their needs.
Our role is to improve access to information and create stronger connections between consumers and the housing marketplace.
Marketplace inclusion means that an institution or product has met the applicable participation standards. It does not mean that the community or Club 720 guarantees the institution, its services, or its suitability for every consumer. Participation should not be interpreted as an exclusive endorsement or recommendation. Consumers should evaluate available options and make the decision that is right for them.
More choice is not always better if it simply creates confusion. Club 720 works to organize the Marketplace around consumer needs and meaningful product differences. Where several lenders offer similar products, Club 720 may consider factors such as:
Marketplace inclusion is not permanent. Housing finance changes. Interest rates change. Programs change. Assistance becomes available or expires. Consumer needs change. Products may therefore be reviewed periodically to determine whether they continue to meet Marketplace standards and serve an identified need. A product may remain active, require additional review, become inactive, or be replaced when a stronger solution becomes available. This helps Club 720 remain a living marketplace rather than a static list of resources.
Lender participation does more than connect individual homebuyers with mortgage products. It helps communities understand their housing finance system. Through Marketplace Activation, communities can begin identifying:
This allows communities to make more informed housing decisions.
Instead of creating a new program simply because a need exists, communities can first ask:
Can the existing marketplace solve this? If the answer is yes, Club 720 helps connect residents to the solution. If the answer is no, the remaining gap becomes clearer.
Join our newsletter and be the first to know about updates, new resources, partner opportunities, and upcoming events.
